Resource Hub
Not Quite Loan-Ready Yet? That's Okay.
Every business starts somewhere. Explore the resources below to help strengthen your business foundation and prepare for future financing opportunities.
Need help taking the first steps?
Starting a business or preparing for financing can feel overwhelming, but you don't have to do it alone. The Small Business Administration (SBA), your local Small Business Development Center (SBDC), or SCORE offer valuable resources, counseling, training, and guidance to help entrepreneurs build a strong foundation.
Whether you're developing your business plan, refining your financials, or getting loan-ready, these organizations are a great place to start. When you are loan-ready, please come back and we'll be here to help.
Our online library, Initiate Prosperity, Powered by CEF, has free, downloadable resources, workbooks, guides, and more for you and your small business. You can access this today, FREE.
Documents Needed - Startup
- Business Plan Template: $50K or Less
- Business Plan: Over $50K
- Cash Flow Worksheet with Instructions
- Cash Flow example
- Debt Service Worksheet
- Personal Financial Statement
- Statement of Ownership
- EIN# Letter
- Lease Agreement or Letter of Intent (if renting the space)
- Proof of Personal Investment (Equity)
Documents Needed - Existing Business
- Cash Flow Worksheet with Instructions
- Cash Flow example
- Balance Sheet
- Debt Service Worksheet
- Personal Financial Statement
- Business Bank Statements
- Business Tax Returns
- Statement of Ownership
Documents Needed from Primary Applicant:
- Personal Bank Statements (3 months)
- Driver's License or State Issued ID
- Document relating to Citizenship Status if not a U.S. Citizen
- Proof of Income (paystub, draw ledger or other verifiable source of income)
- Personal Tax Returns
- Personal Financial Statement
Common Loan Questions
You will need 3 months personal and business bank statements, Cash Projection, your Balance Sheet for an existing business, Business Insurance Showing Coverage, Lease Agreement if applicable, Profit & Loss statement, 2 years personal and business tax returns, Driver License/State Issued ID or Citzenship/Residency docs, Personal Financial Statement, Proof of Income (paystub or draw ledger), Debt Service Worksheet and a Statement of Ownership. We may require additional documentation depending on the collateral, loan size, and quality of the documents provided.
Credit scores are not a hard stop, as we factor in the individual and aspiration where other banks don't. However, if you are a startup, generally, we want to see a score of 650 or higher.
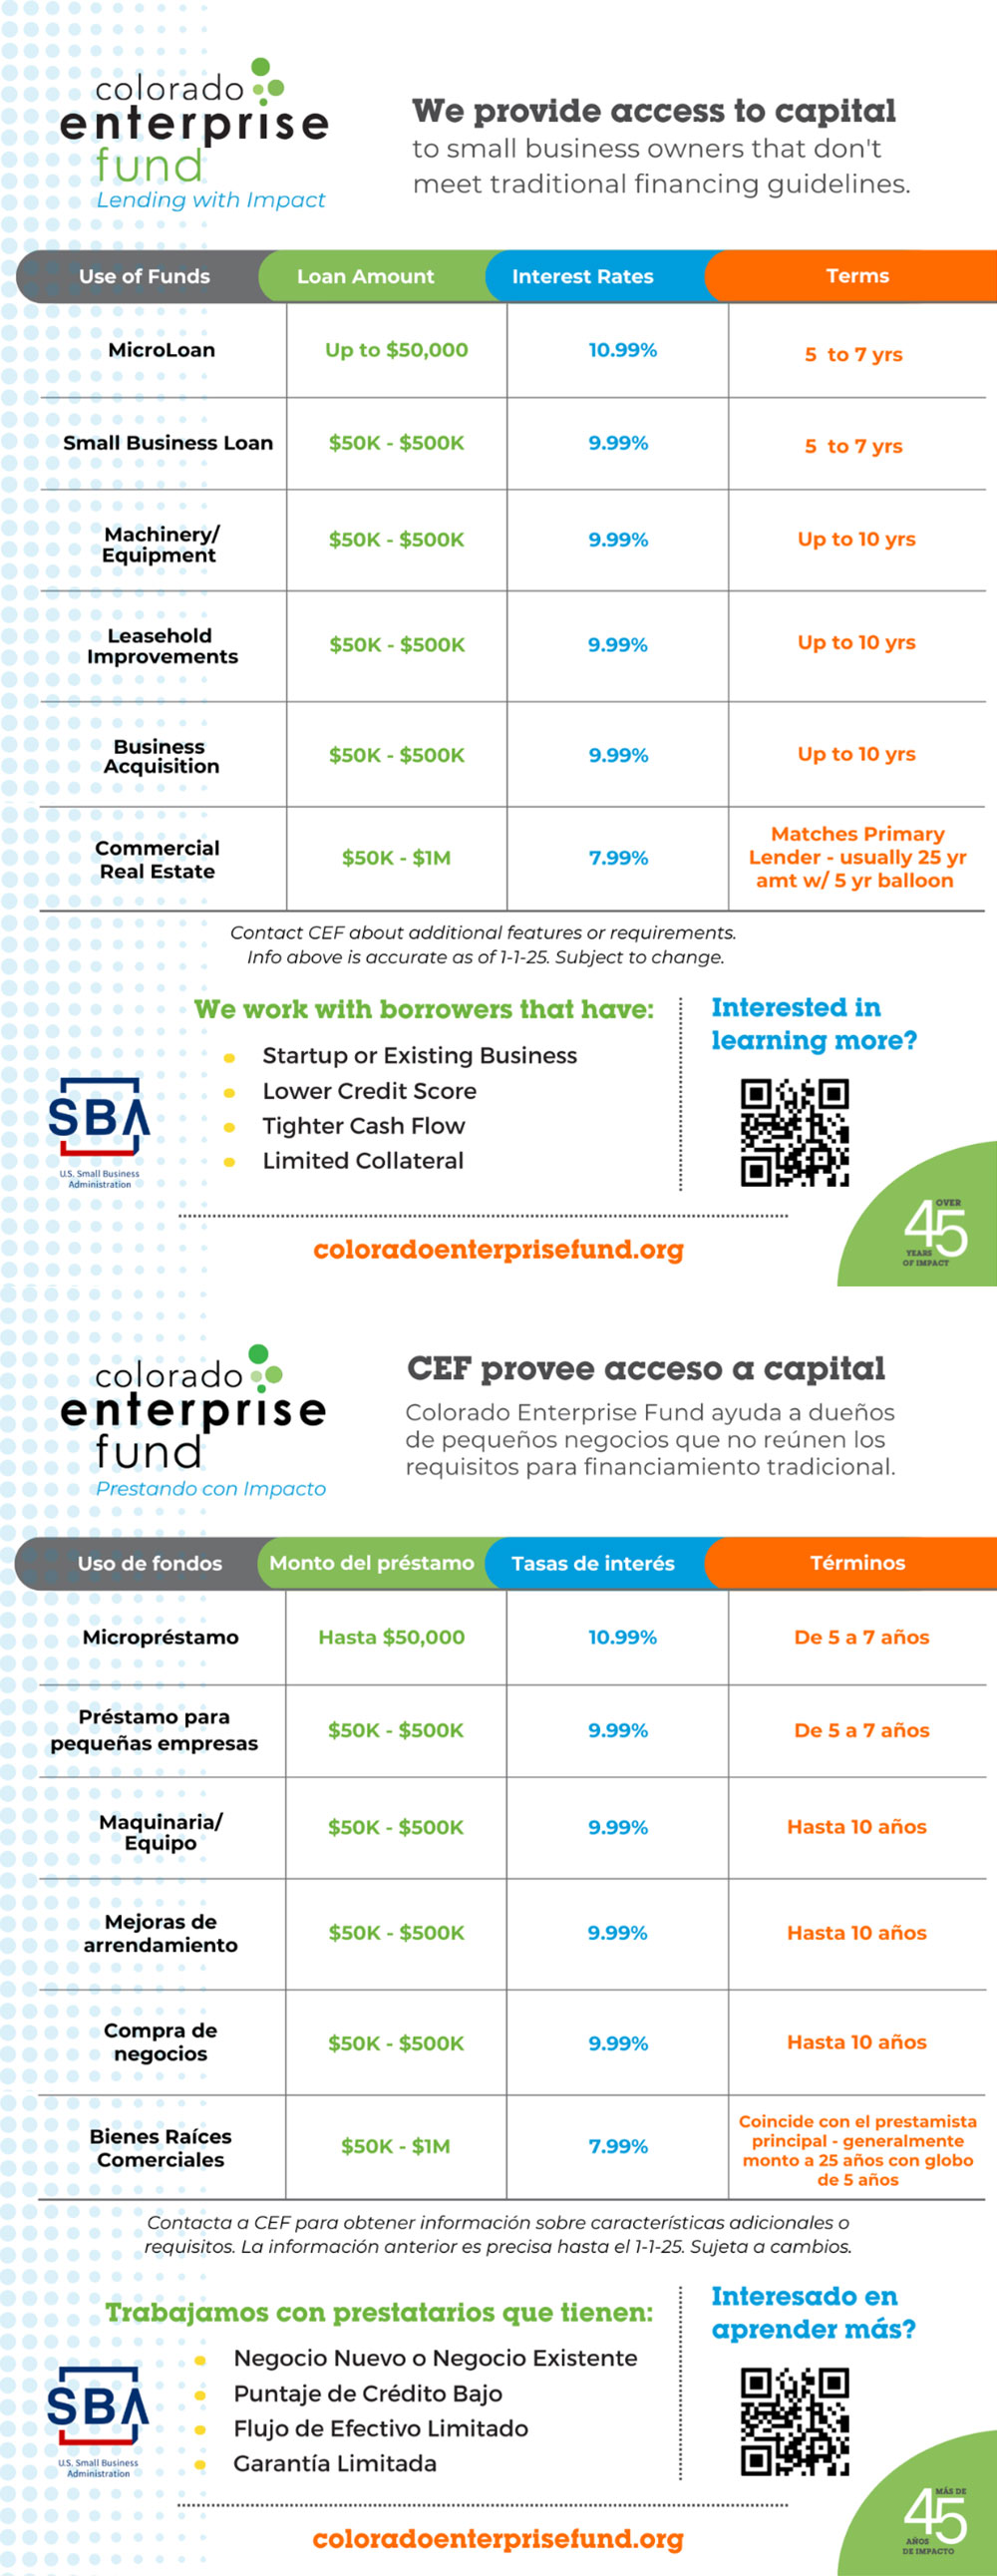
For loan requests over $50,000, CEF will generally review whether the loan may qualify for an SBA 7 (a) loan guarantee. An SBA guarantee can help CEF provide financing to more businesses and may allow for larger loan amounts. Because the SBA process requires additional documentation and review, these loan requests may take longer to approve than smaller loans.
Some industries require additional review and due diligence because of their business model, regulatory requirements, revenue structure, or other underwriting considerations. While these industries may still be eligible for financing, the evaluation process often takes longer to ensure we fully understand the business and its ability to repay the loan.
Industries that commonly require additional due diligence include:
- Distilleries and breweries
- Businesses manufacturing or selling beverages directly to consumers
- Health and wellness businesses, such as red light therapy, sauna, hot tub, and massage services
- Software and app development companies, particularly early-stage or startup ventures with limited operating history
- Consultants without established, proven annual revenue exceeding $50,000
- Trucking and transportation businesses
Additional documentation or a more detailed review may be required for these industries. This does not necessarily mean your business is ineligible; it simply means our underwriting team needs more information before making a lending decision.